
Strategy
March 08, 2024
Return of assets from cyclical consumption companies
DOI: 10.22167/2675-6528-20230127
E&S 2024, 5: e20230127
Lorena Layza Pimenta Oliveira
One of the main objectives of companies is to offer products and/or services that meet market demand and, at the same time, enable positive cash generation. The cyclical consumption segment plays a crucial role in the economic market, as it influences consumption trends and reflects supply and demand dynamics. Companies in this segment offer products and services that are not considered essential by consumers, according to the B3[1] (São Paulo Stock, Exchange, Commodities and Futures) classification, and which are closely linked to consumer behavior.
For this purpose, firms end up needing sources of own or third-party financing. The decision on how to finance activities is based on three fundamental variables: cost, term, and quantity. Based on these aspects, the company forms its equity structure, indicating how much is the participation of third-party capital and how much is own capital to be used in financing its assets. According to the orientation and guidelines of B3[1], companies that opt for third-party capital and lack a credit line must keep their financial information updated and have a good market reputation to demonstrate their ability to repay debts. There are several sources of third-party capital financing in the market, such as debentures, bonds, leases and bank loans, which are part of the company’s interest-bearing liabilities.
In case the company decides to resort to equity capital (capital subscription), going public on the stock exchange is one of the alternatives. This entails numerous advantages, according to B3, such as an increase in market value, facilitation of acquisition and merger processes without needing to disburse cash resources, greater reliability and transparency for investors and shareholders, among others. On the other hand, the B3[1] guide on initial public offering (IPO), or initial public offering, published in 2022 reinforces that, by going public, the company is obliged to provide and disclose information to the market and shareholders, while simultaneously becoming susceptible to financial speculation, which can generate negative impacts on its operations. Therefore, it is of utmost importance for shareholders to carefully analyze whether this strategy will or will not provide advantages aligned with the company’s strategic positioning.
For a company to have securities traded on a stock exchange, it is necessary to comply with and follow all the regulatory requirements listed in the Brazilian Corporations Law, or Law of S.A., n° 6.404/76[2], and, consequently, register with the Securities and Exchange Commission (CVM). Still according to B3[1], the three main prerequisites required are: having three years of financial statements audited by an independent expert registered with the CVM; possessing a board of directors; and fitting into the listing segments. For the subscription process, it is important to choose the issuing bank, which in practice is the financial intermediary. Assaf Neto[3] indicates that, in the primary market (intended for the issuance and sale of new securities), these operations are carried out by one or more non-bank institutions (consortium), such as brokerage firms, multiple banks, distributors, and investment banks.
According to the B3 IPO guide[1], after registration and listing, an informative document is disclosed to investors, generally called a preliminary prospectus, which aims to serve as a basis for some information, such as: description of the offer, estimated timeline, destination of funds raised, among others. In the meantime, considered a reservation period, investors signal to brokers — based on the information provided in the preliminary prospectus — how much money they intend to invest, forming the bookbuilding, which aims to define a fair price for the initial offering. When the initial public offering of shares is launched, the share price is formed by investors in buy and sell bids. This offer is defined as a portion of the joint-stock company (S.A.), which will be traded in the market and distributed among those who already hold controlling interest and those who seek it[4].
Over time, several researchers have evidenced in empirical studies some market anomalies in the face of this stock movement. Ritter’s research[5], for example, evaluated the phenomena of underpricing (offering the stock on its first day below market value) and underperformance (long-term inferior stock performance). Underpricing is therefore defined as an initial bid below the company’s potential value to attract investors and bring high returns at the beginning of trading[6]. In today’s market, this practice can also be adopted due to uncertainty regarding immediate success.
The topic is relevant given the increase in the volume of public offerings in Brazil and investor confidence in the capital market. According to data from B3[1], in 2018 the number of individual investors was around 700,000, while in December 2022, it reached 5 million, representing a 700% increase.
Thus, this research sought to identify underpricing in consumer segment companies in the period 2019–2022. Consumer segment companies are those that produce consumer goods intended for personal or collective use, being of vital importance to the economic market also due to their diversity. This work sought to identify abnormal returns in initial public offerings, using the Ibovespa index as a market reference during the years 2019 to 2022, based on Ritter’s research[5]. This methodology is quite effective and also applicable in the Brazilian market[7]. The analyzed results were grouped into the estimation windows shown in table 1.
Table 1. Pet windows
| Adopted windows — Day | Period | Analysis perspective |
| 0 | 0 | Preliminary prospectus offering |
| 1st | 1 day | Below-market pricing |
| 5th | 5 days | Very short term |
| 21st | 1 month | Very short term |
| 63rd | 3 months | Short term |
| 126th | 6 months | Short term |
| 252nd | 12 months | Long term |
| 378th | 18 months | Long term |
| 504th | 24 months | Long term |
| 756th | 36 months | Long term |
Considering that there is no quotation in the previous period of the IPO and, consequently, an estimation window, the offer value from the preliminary prospectus is presented in relation to the Ibovespa index. In the last four years, 99 companies that launched IPOs in the Brazilian market were identified. The biggest highlight was the year 2021, with 60 companies, representing 61% of the sample (Table 2).
According to B3[1], the classification of cyclical consumption companies is conditioned by the demand for economic conditions or consumer behavior. In contrast, non-cyclical consumption companies provide essential goods and services for daily life.
Table 2. Sectors of companies that launched IPOs in the last four years
| Subsector | 2019 | 2020 | 2021 | 2022 | Total sales (vendas)/ Invoicing (emissão de doc) |
| Cyclical consumer companies | 3 | 11 | 8 | 22 | |
| Information technology | 4 | 9 | 13 | ||
| Financial | 1 | 2 | 10 | 13 | |
| Health | 1 | 3 | 5 | 1 | 10 |
| Non-cyclical consumer companies | 1 | 1 | 8 | 10 | |
| Industrial goods | 1 | 4 | 5 | 10 | |
| Public utility | 1 | 6 | 1 | 8 | |
| Communications | 1 | 4 | 5 | ||
| Basic materials | 1 | 1 | 3 | 5 | |
| Oil, gas and biofuels | 1 | 2 | 3 | ||
| Grand total | 8 | 29 | 60 | 2 | 99 |
The study focused its analysis on companies in the cyclical consumption niche, which are actively influenced by the behavior of economic agents (households, governments, and companies) and, at the same time, by macroeconomic market variations (inflation, interest rates, exchange rates, economic and financial crises, etc.), which is why this segment is highly volatile. At the same time, it demonstrated a broader range of data for the analysis in question.
Table 3 presents the companies that correspond to the study’s sample. For the most part, companies from the commerce and civil construction sectors are observed. The companies Le Biscuit, Kallas Incorporações, and Tegra Incorporadora were excluded from the sample due to a lack of information regarding quotations in the Economática platform’s database, a tool that provides financial information and analyses of companies listed on the Stock Exchange.
Table 3. Companies classified in cyclical consumption that launched IPOs during the years 2019 to 2022
| Subsector | 2019 | 2020 | 2021 | Total sales (vendas)/ Invoicing (emissão de doc) |
| Trade | 2 | 3 | 2 | 7 |
| Allied Technology Corporation | 0 | 0 | 1 | 1 |
| Cea Modas S.A. | 1 | 0 | 0 | 1 |
| Grupo De Moda Soma Corporation | 0 | 1 | 0 | 1 |
| Sbf Group | 1 | 0 | 0 | 1 |
| Lojas Quero-Quero S/A | 0 | 1 | 0 | 1 |
| Mpm Corpóreos S.A. | 0 | 0 | 1 | 1 |
| Pet Center Comercio E Participacoes S.A. | 0 | 1 | 0 | 1 |
| Civil construction | 0 | 7 | 0 | 7 |
| Alphaville S.A. | 0 | 1 | 0 | 1 |
| Cury Construtora E Incorporadora S.A. | 0 | 1 | 0 | 1 |
| Lavvi Real Estate Developments Inc. | 0 | 1 | 0 | 1 |
| Melnick Real Estate Development Inc. | 0 | 1 | 0 | 1 |
| Mitre Realty Investments and Participations S.A. | 0 | 1 | 0 | 1 |
| Moura Dubeux Engenharia S/A | 0 | 1 | 0 | 1 |
| Plano & Plano Real Estate Development S.A. | 0 | 1 | 0 | 1 |
| Several | 0 | 0 | 3 | 3 |
| Cruzeiro Do Sul Educational S.A. | 0 | 0 | 1 | 1 |
| Dotz S.A. | 0 | 0 | 1 | 1 |
| Vamos Truck Rental. Machinery And Equip. S.A. | 0 | 0 | 1 | 1 |
| Textiles, clothing and footwear | 1 | 1 | 0 | 2 |
| Track & Field Corporation | 0 | 1 | 0 | 1 |
| Vivara Participações S.A | 1 | 0 | 0 | 1 |
| Grand total | 3 | 11 | 5 | 19 |
Asset prices were extracted from Economática. Starting from the quotes, five steps were taken:
- Calculation of the daily asset return
The buying and selling operations of an asset are traded by the minute, by the instant, or throughout the day, called intraday quotes[8]. In view of this, as it is a continuous capitalization, the daily return of an asset or its profitability is calculated from the Log return, measured by the following relationship:
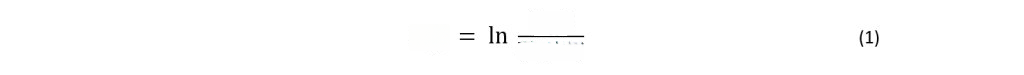

- Calculation of abnormal asset return
After calculating the identified returns, the abnormal returns were calculated by the difference between the company’s return subtracted from the Ibovespa variation in the same period.
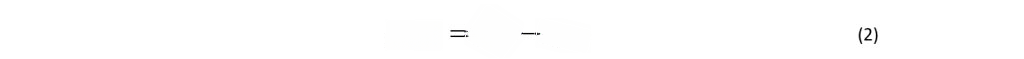

Abnormal returns can also be called excess returns or alpha and are named this way because they highlight the unexpected profits or losses of a given asset or portfolio in a given period. Abnormal returns are excellent indicators for measuring risk-adjusted asset performance relative to the benchmark index, in this case the Ibovespa.
- Calculation of the accumulated abnormal return
The cumulative abnormal return (CAR) [is the sum of all abnormal returns[/0]].
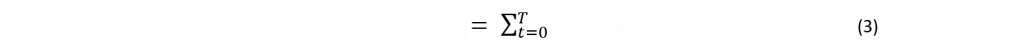

- Calculation of the average abnormal return
The next step was to estimate the average CAR of the sample through a simple arithmetic mean.
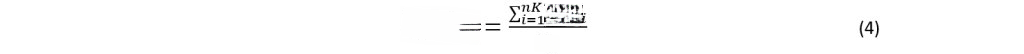

- Hypothesis testing
The procedure for the test used in this research, according to Campbell et al.[9], was applied to the abnormal returns calculated. The results of the statistical test were obtained using Microsoft Excel.
The statistical test was used based on the mean of the abnormal return and the accumulated return. In this research, the following hypotheses were tested:
- null hypothesis (H0): mean of abnormal returns (AR) and cumulative average abnormal returns (CAR) equal to zero;
- alternative hypothesis (HA): mean of abnormal returns (AR) and cumulative average abnormal returns (CAR) different from zero.
The statistical significance tests for AR and CAR (average abnormal returns) were defined by t statistic, according to the formulas indicated below:
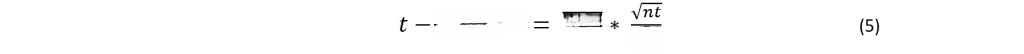

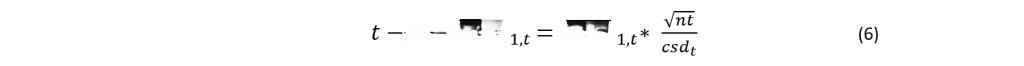

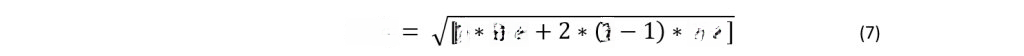

According to the data presented in Table 4, below, it was possible to observe returns of individual assets on the first trading day, comparing returns of individual assets versus the price in the prospectus to the price that was established in the preliminary prospectus (benchmark 0). The results indicated that the asset was issued at a price lower than what could have been established, from Alphaville (0.17%), CEA (2.28%), Curry (2.5%), Mitre (7.08%), MPM (13.77%), Petz (20.21%), Plano (20.21%), Quero-Quero (0.45%), Soma (12.83%), Track (0.24%), and Vamos (21.01%).
Table 4. Return on assets (AR)
| Day | Company | Day 01 (event) |
| 2019 | CEA Modas S.A. | 2,28% |
| 2019 | Grupo SBF Corp. | -0,50% |
| 2019 | Vivara Participações S.A. | -3,55% |
| 2020 | Alphaville S.A. | 0,17% |
| 2020 | Cury Construtora e Incorporadora S.A. | 2,50% |
| 2020 | Grupo de Moda Soma Corporation | 12,83% |
| 2020 | Lavvi Real Estate Developments Inc. | -5,16% |
| 2020 | Lojas Quero-Quero S.A. | 0,45% |
| 2020 | Melnick Real Estate Development Inc. | 0,65% |
| 2020 | Mitre Realty Developments and Holdings | 7,08% |
| 2020 | Moura Dubeux Engenharia S.A. | -1,80% |
| 2020 | Pet Center Comércio e Participações S.A. | 20,21% |
| 2020 | Plano & Plano Real Estate Development S.A. | 20,21% |
| 2020 | Track & Field Corporation | 0,24% |
| 2021 | Allied Technology Corporation | -5,63% |
| 2021 | Cruzeiro do Sul Educational S.A. | -8,29% |
| 2021 | Dotz S.A. | -0,52% |
| 2021 | MPM Corpóreos S.A. | 13,77% |
| 2021 | Vamos Truck Rental S.S. | 21,01% |
When analyzing the average abnormal return of the portfolio on the first day of the event, a positive return of 4% was found, according to Table 5, characterizing the underpricing phenomenon in IPOs, with a significance level of 5%. Therefore, hypothesis H0 was rejected, confirming the positive abnormal return on the first day of the event.
In the long term, negative returns were identified in the first month (-0.74%) and six months after the initial offering (-0.94%). In contrast, there was a portfolio gain of 2.43% after 36 months.
Table 5. Average of abnormal returns
| Period | AR* average | Test statistic | tabulated (95%) | Significance |
| Day 1 | 4,00% | 1,90 | -1,73 | No |
| 5 days | 0,25% | 0,58 | -1,73 | No |
| 1 month | -0,74% | -0,60 | -1,73 | No |
| 3 months | 0,17% | 0,21 | -1,73 | No |
| 6 months | -0,94% | -1,54 | -1,73 | No |
| 12 months | 0,36% | 0,41 | -1,73 | No |
| 18 months | 0,52% | 0,76 | -1,73 | No |
| 24 months | 0,58% | 0,69 | -1,76 | No |
| 36 months | 2,43% | 1,51 | -2,92 | No |
Note: *AR = asset return
Table 6 shows the average accumulated returns, adjusted by Ibovespa, considering the periods: milestone 0 (preliminary prospectus), first day, five days, one, three, six, 12, 18, 24, and 36 months. The sample analysis found negative average accumulated abnormal returns, meaning there was a loss in portfolio value:
- First month: -15.10%.
- Three months: -15.77%.
- 12 months: -22.97%.
- 18 months: -55.63%.
- 24 months: -74.74%.
- 36 months: -118.14%.
The loss did not present a statistically significant degree, which suggests the presence of the phenomenon underperformance, reported in the literature by Ritter[5], Silva and Famá[7] and other authors.
Table 6. Average cumulative returns (CAR)
| Period | Accumulated CAR | Test statistic | tabulated (95%) | Significance |
| Day 0 | -13,10% | -2,17 | -1,73 | Yes |
| Day 1 | -9,10% | -4,33 | -1,73 | Yes |
| 5 days | -10,14% | -23,10 | -1,73 | Yes |
| 1 month | -15,10% | -12,22 | -1,73 | Yes |
| 3 months | -15,77% | -19,88 | -1,73 | Yes |
| 6 months | -19,99% | -32,77 | -1,73 | Yes |
| 12 months | -22,97% | -26,44 | -1,73 | Yes |
| 18 months | -55,63% | -80,71 | -1,73 | Yes |
| 24 months | -74,74% | -88,62 | -1,76 | Yes |
| 36 months | -118,14% | -73,35 | -2,92 | Yes |
Silva and Fama[7] concluded that the positive results in the early days were due to the high expectations of investors. In the study, however, it was perceived that in the long term there was a return below what was expected by them. However, it should be noted that, in the analyzed period, the economy suffered a global financial crisis due to the covid-19 pandemic, which included the capital market.
The objective of this research was to identify Brazilian companies in the cyclical consumption segment that launched an IPO during the period from 2019 to 2022 and to identify the underpricing at the capital opening of these companies.
The results of this study showed an abnormal return of the asset on the first day of the offering, with the phenomenon of underpricing being observed. However, when analyzing the accumulated CAR based on the mark 0 disclosed in the preliminary prospectus, a significant long-term devaluation was observed, widely characterized in the market as underperformance.
The long-term devaluation of the stock may be associated with the return of the price to the fair value of the stock[5]; its overvaluation would occur due to high investor expectations at the IPO launch. Furthermore, companies’ operational performance, economic recession, pandemics, environmental crises, interest rates, and high inflation are also considered factors that can lead to a retraction of investors and potential interested parties.
Some limitations identified in this study were the short period analyzed and the exclusion of international companies that launched IPOs. Furthermore, a temporal forecast of the return of these assets for the current year could be an addition and serve as a parameter for investors’ decision-making. For future research, it is suggested to analyze sectoral activity indicators and operate with portfolios whose assets have a weight proportional to their market value.
References
[1] B3. Guia do IPO. Disponível em: https://www.b3.com.br/pt_br/produtos-e-servicos/solucoes-para-emissores/abertura-de-capital/como-abrir-o-capital/. Acesso em: 15 mar. 2023.
[2] Brasil. Lei nº 6.404, de 15 de dezembro de 1976. Lei das Sociedades Anônimas; Lei das S.A.; Lei das S/A; Lei das Sociedades por Ações; Lei das Companhias por Ações. Diário Oficial da União, 1976 dez. 17. Lei das sociedades anônimas, pág. 1. Disponível em: https://www2.camara.leg.br/legin/fed/lei/1970-1979/lei-6404-15-dezembro-1976-368447-norma-pl.html. Acesso em: 19 fev. 2024.
[3] Assaf Neto A. Finanças corporativas e valor. 3ed. São Paulo (SP): Atlas; 2007.
[4] Cruz E.F.; Camargos M.C.S.; Camargos M.A. Underpricing e underperformance em estratégias de investimento em aberturas de capital na BM&FBOVESPA, 2004-2013. In: Anais do XXXVI Encontro Nacional de Engenharia de Produção; 2016; João Pessoa, PB, Brasil. Disponível em: https://www.abepro.org.br/biblioteca/TN_STP_228_333_29775.pdf. Acesso em: 19 abr. 2023.
[5] Ritter J.R. The long-run perfomance of initial public offering. Journal of Finance. 1991; 46: 3-27. DOI: 10.1111/j.1540-6261.1991.tb03743.x. Acesso em: 21 fev. 2023.
[6] Oliveira B.C.; Kayo E.K. Desempenho de ações de empresas brasileiras após seu IPO: evidências de curto e de longo prazo. REGE: Revista de Gestão. 2015; 22: 173-186. DOI: 10.5700/rege557.
[7] Silva J.M.A.; Famá, R. Evidências de retornos anormais nos processos de IPO na Bovespa no período de 2004 a 2007: Um estudo de evento. Revista de Administração. 2020; 46(2): 178-190. DOI: 10.5700/rausp1006.
[8] Lima F.G. Análise de Riscos. 2ed. São Paulo (SP): Atlas . 2018. 440 p.
[9] Campbell J.Y.; Lo A.W.; Mackinlay A.C. The econometrics of financial markets. New Jersey (NJ): Princeton University Press; 1997. 611 p.
Como citar
Oliveira L.L.P. Retorno dos ativos de empresas do consumo cíclico. Revista E&S. 2024; 5: e20230127.
Sobre os autores
Lorena Layza Pimenta Oliveira , Rodovia BA-512, s/n – CEP 42800-000, Camaçari/BA, Brasil.
Download link: PDF